Co-Investment in AIFs: How It Works and Who Can Participate

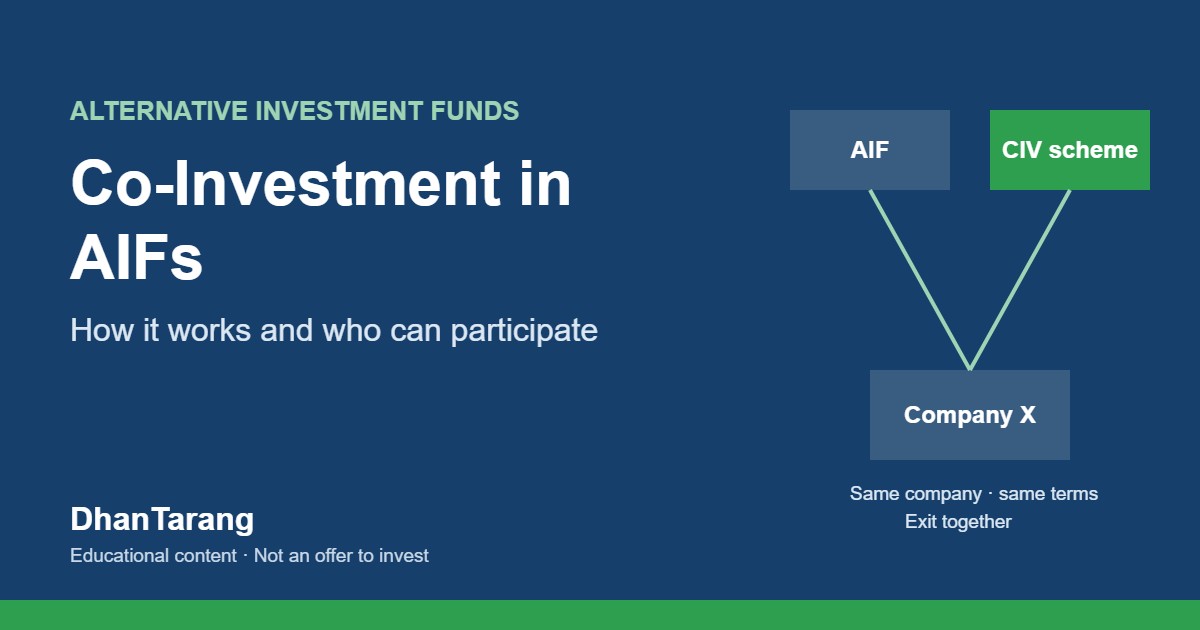
Co-investment in AIFs – AIF and CIV scheme investing in the same company on the same terms

Key takeaways

  • Co-investment lets an investor in an AIF put additional money directly into a specific unlisted company that the AIF is investing in or has invested in.
  • Since September 2025, Category I and II AIFs can offer co-investment through a separate Co-Investment Vehicle (CIV) scheme, in addition to the existing portfolio management (PMS) route.
  • Only accredited investors of the AIF can invest through a CIV scheme.
  • An investor’s co-investment in a company is capped at three times their contribution to the AIF’s investment in that company.
  • Co-investors get the same terms as the AIF, never better, and must exit at the same time as the AIF.

Imagine you have invested in a private equity fund, and the fund manager finds a company they believe in strongly. The fund can only put a limited amount into one company, but you would like a bigger stake in that particular deal. Co-investment is how you can do that. Until recently, the route in India was complex. SEBI’s September 2025 framework created a simpler structure inside the AIF regulations themselves. This guide explains how co-investment works, who is allowed to participate, and what rules protect co-investors.

What is co-investment in an AIF?

Co-investment in an AIF means offering the fund’s own investors an opportunity to invest additional money in the unlisted securities of a company where the AIF is also investing or has already invested. The investor holds a larger stake in that one company than their share of the fund alone would give them.

In a normal AIF investment, your money is spread across all the companies the fund backs. In a co-investment, you choose to put extra money into one specific company, alongside the fund, on the same terms. It is common in private equity and venture capital worldwide, especially for large deals where the fund wants to bring in more capital without exceeding its own concentration limits.

Why do investors choose to co-invest?

Investors co-invest to increase exposure to a specific company they have conviction in, while relying on the AIF manager’s research, negotiation and monitoring. The investment is made on the same terms the AIF receives, and the co-investor exits when the fund exits.

  • Targeted exposure: a larger position in one company, rather than only a diversified share of the fund.
  • Manager-led due diligence: the deal has already been researched and negotiated by the fund manager.
  • Aligned terms: co-investors invest on the same terms as the AIF, and SEBI does not allow better terms for co-investors.
  • Choice: co-investment is optional and offered deal by deal, so you decide which opportunities to take.

What are the two routes for co-investment in India?

Managers of Category I and II AIFs can offer co-investment through one of two routes: the portfolio management (PMS) route under the SEBI (Portfolio Managers) Regulations, 2020, or the Co-Investment Vehicle (CIV) scheme route introduced in September 2025 under the AIF regulations.

PMS routeCIV scheme route
Regulated underSEBI (Portfolio Managers) Regulations, 2020SEBI (AIF) Regulations, 2012 (Regulation 17A)
IntroducedExisting routeSeptember 2025
Manager requirementManager must also register as a portfolio managerWorks within the AIF structure
Who can investAs per PMS rules; confirm eligibility with the managerOnly accredited investors of the AIF
StructureInvestment managed through a PMS accountSeparate scheme for each co-investment, with ring-fenced bank and demat accounts

The CIV route is generally simpler for managers, because they do not need a separate portfolio manager registration to offer co-investment.

What is a CIV scheme?

A Co-Investment Vehicle (CIV) scheme is a scheme launched by a Category I or Category II AIF to let its investors co-invest in the unlisted securities of a company where the AIF is investing or has invested. Each CIV scheme is created for one investment only and invests in only one company.

Because a CIV scheme is tied to a single deal, a new one must be launched for every co-investment, and it can be wound up once the investment is exited. Each scheme keeps separate bank and demat accounts, so its assets are ring-fenced from the main fund and from other CIV schemes. Angel funds cannot launch CIV schemes.

Who can participate in AIF co-investment?

Under the CIV route, only accredited investors who are already investors in the eligible AIF can co-invest. Investors who have been excused, excluded or have defaulted on their contributions to the AIF cannot co-invest in that company. You cannot join a CIV scheme without first being an investor in the main fund.

An accredited investor is someone certified by a SEBI-recognised accreditation agency as meeting income or net-worth thresholds. The current criteria for resident investors are:

Route to accreditationThreshold
Individuals, HUFs, family trusts, sole proprietors: income onlyAnnual income of at least ₹2 crore
Individuals and others: net worth onlyNet worth of at least ₹7.5 crore, with at least ₹3.75 crore in financial assets
Individuals and others: income plus net worthAnnual income of at least ₹1 crore and net worth of at least ₹5 crore, with at least ₹2.5 crore in financial assets
Body corporatesNet worth of at least ₹50 crore

The value of your primary residence is not counted in net worth. Note that SEBI issued a consultation paper on 13 August 2026 proposing changes to the accredited investor framework, including manager-led accreditation and a new securities-assets route. These are proposals only, and the criteria above apply until SEBI notifies any change.

How much can you co-invest?

Your co-investment in a company, across all CIV schemes, cannot exceed three times the amount you contributed through the main AIF scheme towards the AIF’s investment in that same company. This cap does not apply to certain institutional investors, such as sovereign wealth funds, development financial institutions and government-owned entities.

An illustration: suppose the AIF invests ₹20 crore in Company X, and your share of the fund means ₹40 lakh of that came from your contribution. Your maximum co-investment in Company X through CIV schemes would be three times ₹40 lakh, or ₹1.2 crore. (Illustrative figures only.)

What rules protect co-investors?

SEBI’s framework sets conditions to keep co-investment fair to both co-investors and the AIF’s other investors:

  • Same terms, never better: co-investment terms cannot be more favourable than the AIF’s own terms in that company.
  • Exit together: co-investors must exit the company at the same time as the AIF.
  • No leverage: a CIV scheme cannot borrow or use leverage.
  • Pro-rata rights: investors in a CIV scheme get pro-rata rights and pro-rata distribution of proceeds.
  • Fair cost sharing: expenses of the co-investment are shared between the AIF scheme and the CIV scheme in proportion to their investments.
  • Full disclosure: before offering any co-investment, the manager must file a Shelf Placement Memorandum with SEBI through a merchant banker, disclosing the principal terms, allocation method, expenses, conflicts of interest and governance structure.
  • No regulatory shortcuts: a CIV scheme cannot be used to make investments an investor could not make directly, or to avoid disclosures that a direct investment would trigger.
  • Oversight: the manager reports compliance to the trustee and sponsor in the annual compliance test report.
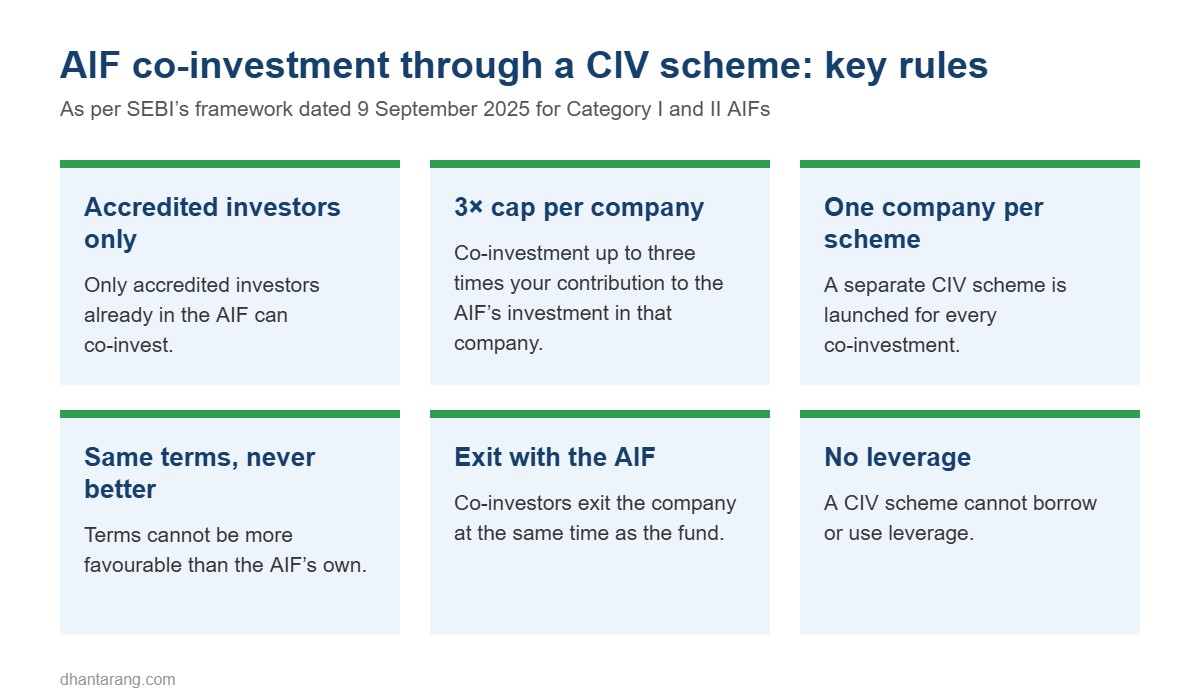
Infographic of SEBI rules for AIF co-investment through a CIV scheme
Six key rules for co-investment through a CIV scheme, as per SEBI’s September 2025 framework.

SEBI’s Master Circular for AIFs dated 3 June 2026 consolidates these instructions in one place.

How does co-investment work, step by step?

  1. Invest in the AIF. You first become an investor in a Category I or II AIF that offers co-investment.
  2. Get accredited. Obtain an accreditation certificate from a SEBI-recognised accreditation agency, if you do not already hold one.
  3. Receive the opportunity. When the fund invests in a company and offers co-investment, the manager shares the terms under the Shelf Placement Memorandum.
  4. Decide and commit. You choose whether to participate and how much, within the three-times cap.
  5. Invest through the CIV scheme. A separate CIV scheme is launched for that company, with its own accounts.
  6. Exit with the fund. When the AIF exits the company, the CIV scheme exits too, and proceeds are distributed pro-rata.

What are the risks of co-investment?

Co-investment concentrates your money in a single unlisted company, so it carries more risk than your diversified AIF holding. If that one company performs poorly, there are no other holdings in the CIV scheme to balance the loss.

  • Concentration risk: a CIV scheme holds only one company.
  • Liquidity risk: you can exit only when the AIF exits, which may take several years.
  • Valuation risk: unlisted companies are valued periodically, not daily.
  • Allocation and conflict risk: check how the manager decides who gets co-investment opportunities and how much, as disclosed in the Shelf Placement Memorandum.
  • Overexposure: co-investing in a company you already hold through the AIF increases your total exposure to that one business.

Questions to ask before you co-invest

  1. Is the co-investment through the PMS route or a CIV scheme?
  2. What is my existing exposure to this company through the main fund, and what would my total be?
  3. How are co-investment opportunities allocated among investors?
  4. What expenses and fees apply to the CIV scheme, and how are they shared with the main fund?
  5. What is the expected holding period, and when is the AIF likely to exit?
  6. How will returns from the co-investment be taxed in my hands? Confirm with your tax adviser.

Frequently asked questions

What is co-investment in an AIF?

Co-investment is an opportunity for an AIF’s investors to put additional money directly into a specific unlisted company that the AIF is investing in or has invested in, on the same terms as the AIF.

Who can co-invest through a CIV scheme?

Only accredited investors who are already investors in the eligible Category I or II AIF. Investors who have been excused, excluded or have defaulted on their contributions cannot co-invest in that company.

When did SEBI introduce CIV schemes?

SEBI notified the AIF (Second Amendment) Regulations, 2025 on 8 September 2025 and issued the operational framework through its circular dated 9 September 2025.

Is there a limit on how much I can co-invest?

Yes. Your co-investment in a company across all CIV schemes cannot exceed three times your contribution to the AIF’s investment in that company. The cap does not apply to certain institutional investors, such as sovereign wealth funds.

Can a CIV scheme invest in more than one company?

No. Each CIV scheme is investment-specific and invests in only one company. A separate CIV scheme is launched for every co-investment.

Can co-investors exit earlier than the AIF?

No. Co-investors must exit the company at the same time as the AIF, so the co-investment follows the fund’s exit timeline.

Co-investment: more conviction, more concentration

Co-investment gives accredited AIF investors a regulated way to back the deals they believe in most, on the same terms as the fund. It also concentrates risk in a single unlisted company, so it suits investors who already have a diversified portfolio and can stay invested until the fund exits.

DhanTarang Fintech Pvt Ltd, based in Mumbai, helps investors understand alternative investments and how they fit alongside mutual funds and PMS. Learn about Alternative Investment Funds or talk to our team.

Sources

  1. SEBI circular: Framework for AIFs to make co-investment within the AIF structure (9 September 2025)
  2. Saraf and Partners: SEBI frameworks for Angel Funds and Co-Investment Vehicles
  3. AZB & Partners: SEBI Co-Investment Scheme Framework
  4. Cyril Amarchand Mangaldas: SEBI unlocks co-investment schemes for AIFs
  5. Outlook Business: SEBI gives flexibility to AIFs to offer co-investment
  6. Upstox: SEBI’s rules for accreditation of investors
  7. CorpLawUpdates: SEBI consultation on the Accredited Investor framework (2026)
  8. SEBI: AIF circulars and Master Circular (3 June 2026)

Disclaimer: This article is for general information and education only. It is not an offer, solicitation or recommendation to invest in any Alternative Investment Fund. AIFs are offered only through private placement to eligible investors on the basis of a Private Placement Memorandum (PPM), which should be read carefully along with all scheme documents. AIF investments carry market, liquidity and credit risks, and past performance is not indicative of future returns. Tax treatment is subject to change; consult a tax adviser. DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor, ARN-343986.
Mutual Fund Nomination Rules 2026: What Changed on 1 September

Mutual fund nomination rules 2026 – up to 3 nominees, no witness, nominate or opt out

Key takeaways

  • New nomination rules for mutual fund folios and demat accounts apply from 1 September 2026, under SEBI’s circular dated 29 May 2026.
  • Every new single-holder folio must have a nominee unless you sign an opt-out declaration. For joint folios, nomination stays optional.
  • You can name up to three nominees and change them as often as you like.
  • No witness is needed when you sign the form, except if you use a thumb impression.
  • A nominee does not automatically become the owner. Your legal heirs still inherit, so a nomination works best alongside a will.

Every year, money in mutual funds goes unclaimed because an investor passed away without naming a nominee. Families then face months of paperwork to prove their right to the units. SEBI’s new nomination rules, effective 1 September 2026, aim to fix this by making nomination the default and the process much simpler. Here is what changed and what you should do about it.

What are the new mutual fund nomination rules?

The new mutual fund nomination rules come from SEBI’s circular dated 29 May 2026 and apply from 1 September 2026. They make nomination the default for new single-holder folios, allow up to three nominees, remove the witness requirement for signed forms, and make most nominee details optional. They replace SEBI’s earlier nomination circulars, including the one issued in January 2025.

The same rules apply to demat accounts, so if you hold shares or ETFs as well as mutual funds, everything in this guide applies there too.

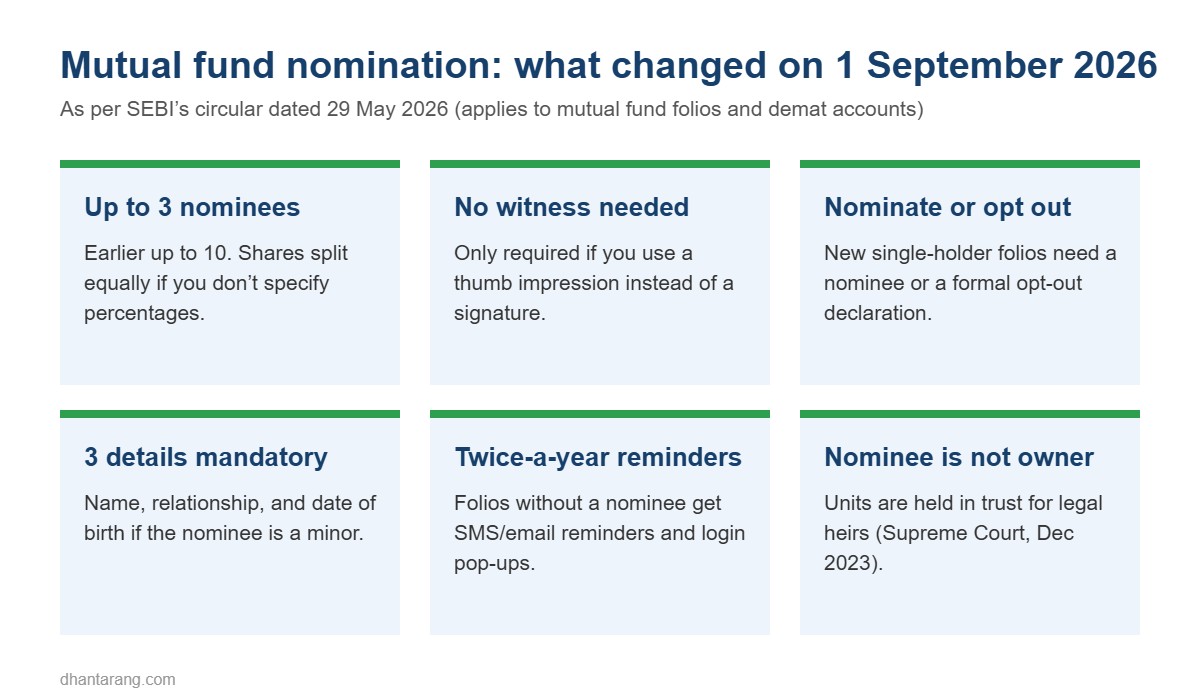
Infographic of key mutual fund nomination rule changes from 1 September 2026
Six key changes in SEBI’s mutual fund nomination rules, effective 1 September 2026.

Is nomination mandatory for mutual funds now?

For new single-holder folios opened on or after 1 September 2026, yes. You must either name a nominee or submit a formal declaration opting out of nomination. For jointly held folios, nomination remains optional.

Two points are worth knowing about joint folios:

  • If joint holders do choose to add or change a nominee, all joint holders must consent, whatever the mode of holding.
  • In a joint folio, the surviving holder usually continues the investment, so many joint investors still add a nominee to cover the case where all holders pass away.

How many nominees can you add?

You can add up to three nominees per folio and specify what percentage each one receives. If you do not specify shares, the units are divided equally among the nominees, with any indivisible remainder going to the first nominee named. You can add, change or cancel nominees any number of times.

This is a change from the January 2025 framework, which allowed up to ten nominees. Three is enough for most families, and it keeps claims simpler.

What details do you need to give for a nominee?

Only three details are now mandatory. Everything else is optional, which makes nomination much quicker than before.

DetailMandatory or optional
Nominee’s nameMandatory
Relationship with the investorMandatory
Date of birth (only if the nominee is a minor)Mandatory
Percentage share for each nomineeOptional (equal split if not given)
Nominee’s KYC identifier (PAN, Aadhaar, etc.)Optional
Guardian’s KYC details (for a minor nominee)Optional
Nominee’s contact detailsOptional

Optional does not mean unimportant. Adding a nominee’s PAN and phone number makes it easier for the fund house to verify and reach them at the time of a claim.

Do you still need a witness to nominate?

No, not if you sign the form. Under the new rules, a witness is needed only when the investor uses a thumb impression instead of a signature. Online nominations can be authenticated with an Aadhaar-based e-signature, a digital signature certificate, or two-factor authentication using a one-time password (OTP).

What changed compared with the earlier rules?

PointEarlier frameworkFrom 1 September 2026
New single-holder folioChoice of nomination requiredNomination by default, or a formal opt-out declaration
Maximum nomineesUp to 10Up to 3
Witness for signed physical formRequiredNot required (only for thumb impression)
Nominee KYC detailsRequiredOptional
Changes to nominationAllowedAllowed any number of times, with acknowledgement each time
Reminders if no nominee—Twice a year by SMS/email, plus pop-ups on login

What if you already have mutual funds without a nominee?

Your existing investments are not frozen, and you can keep investing. But if a folio has no nominee, the fund house or registrar will now remind you twice a year by SMS or email, and you may see pop-up reminders when you log in, until you register a nominee. Your account statement will also show either your nominees’ names or a simple Yes/No for nomination, depending on your choice.

Folios opened years ago are the ones most likely to be missing a nominee, especially those started before nomination became part of standard onboarding. Check every folio, not just the latest one.

Does the nominee become the owner of your mutual funds?

No. In its judgment of 14 December 2023 in Shakti Yezdani v. Jayanand Jayant Salgaonkar, the Supreme Court held that a nominee of shares or mutual fund units does not become the absolute owner. The nominee receives the units and holds them in trust for the legal heirs, who inherit according to succession law or a valid will.

In practice, nomination makes the transfer fast, and a will decides who finally owns the money. If you want a particular person to inherit your investments, name them as nominee and also say so in your will.

How to add or update a nominee in your mutual funds

  1. List all your folios. A consolidated account statement (CAS) shows every folio under your PAN across fund houses.
  2. Check the nomination status of each folio on your account statement or the fund house’s website.
  3. Decide on your nominees and the share each should receive. Keep their name, relationship and, for a minor, date of birth ready.
  4. Submit the nomination online through the fund house or registrar (such as CAMS or KFintech), authenticating with OTP or Aadhaar e-sign, or through your distributor.
  5. Keep the acknowledgement. Every nomination, change or cancellation must now be acknowledged.
  6. Tell your nominees. A nominee who does not know about the investment cannot claim it.

Common nomination mistakes to avoid

  • Nominating only some folios. Each folio needs its own nomination.
  • Opting out without thinking. An opt-out declaration is a valid choice, but it means your family will need legal documents to claim the units.
  • Never updating nominees. Review nominations after marriage, divorce, the birth of a child or a death in the family.
  • Relying on nomination instead of a will. Nomination speeds up the transfer; a will decides ownership.

Frequently asked questions

From when do the new mutual fund nomination rules apply?

The new rules apply from 1 September 2026. They were issued through SEBI’s circular dated 29 May 2026 and cover both mutual fund folios and demat accounts.

Is it compulsory to add a nominee in a mutual fund?

For a new single-holder folio opened on or after 1 September 2026, you must either add a nominee or submit a formal opt-out declaration. For jointly held folios, nomination is optional.

Can I add more than one nominee to a mutual fund folio?

Yes. You can add up to three nominees and specify each one’s percentage share. If you do not specify shares, the units are split equally among them.

Do I need a witness to add a nominee?

No, if you sign the nomination form. A witness is required only when you use a thumb impression. Online nominations are authenticated through OTP, Aadhaar e-sign or a digital signature.

Will my mutual fund folio be frozen if I have not added a nominee?

No. Existing folios without a nominee are not frozen. You will, however, receive reminders twice a year until you add a nominee or confirm that you do not want to.

Does a nominee get full ownership of mutual fund units?

No. As per the Supreme Court’s December 2023 judgment, a nominee holds the units in trust for the legal heirs. Ownership is decided by succession law or the investor’s will.

Make your investments easy to pass on

Nomination takes a few minutes, and it can save your family months of paperwork. Check every folio, name your nominees, and pair your nomination with a will.

DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor (MFD) based in Mumbai. Our team can help you review the nomination status of all your folios and update them in one go. Explore our mutual fund services, complete your KYC or talk to our team.

Disclaimer: Mutual Fund investments are subject to market risks, read all scheme related documents carefully. This article is for general information only and is not investment, tax or legal advice. For succession or estate planning, consult a qualified legal professional. DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor, ARN-343986.
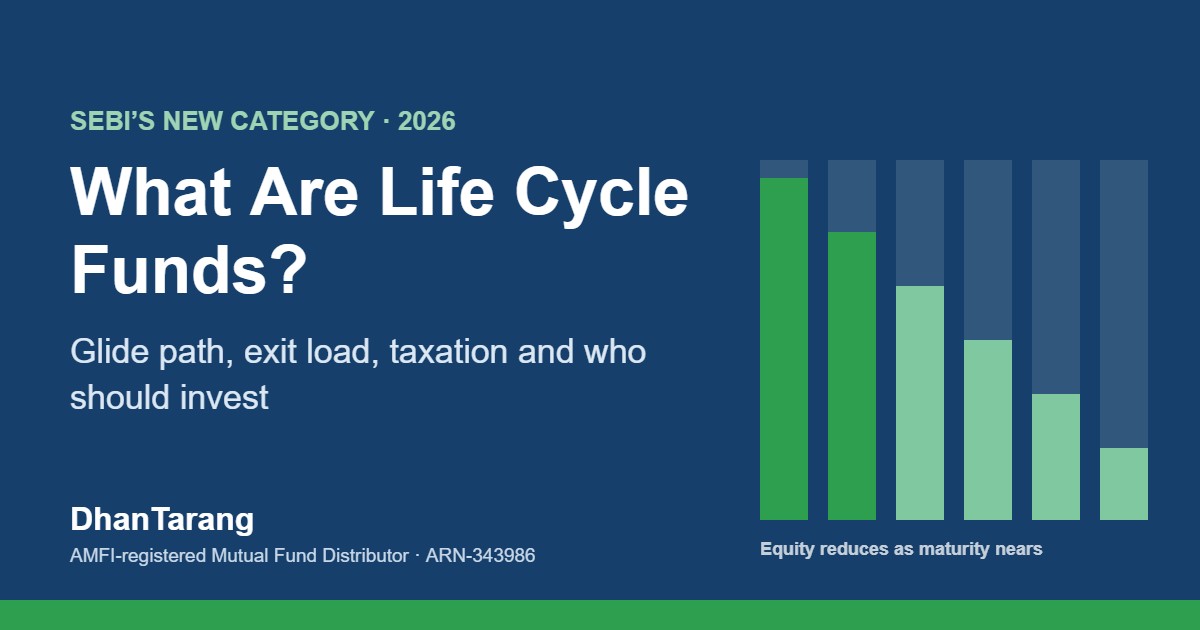
What Are Life Cycle Funds? SEBI’s New Mutual Fund Category Explained

Life Cycle Funds explained – SEBI new mutual fund category with glide path

Key takeaways

  • Life Cycle Funds are a new mutual fund category introduced by SEBI on 26 February 2026 for goal-based investing.
  • Each fund has a fixed maturity of 5, 10, 15, 20, 25 or 30 years, and the maturity year is part of its name.
  • The fund automatically shifts from equity towards debt as maturity approaches, following a glide path set by SEBI.
  • Early exits are discouraged with an exit load of 3%, 2% and 1% in the first three years, and nil after that.
  • They suit goals with a fixed date, such as retirement or a child’s higher education.

Most investors know they should reduce risk as a goal gets closer, but very few actually do it. Equity that should have been moved to safer assets two years before a child’s college admission often stays in the market, and a single bad year can hit exactly when the money is needed. Life Cycle Funds are SEBI’s answer to this problem. This guide explains how they work, who they suit, and what to check before you invest.

What is a Life Cycle Fund?

A Life Cycle Fund is an open-ended mutual fund with a fixed target maturity year, such as 2036 or 2056. It invests heavily in equity when the goal is far away and gradually shifts to debt as the maturity year approaches. This automatic change in asset mix is called a glide path, and SEBI prescribes its limits.

Around the world, the same idea is known as a target-date fund and is widely used for retirement savings. In India, SEBI introduced it as a formal category through its circular of 26 February 2026 on the categorisation and rationalisation of mutual fund schemes. The first Life Cycle Funds were launched in June 2026, and more fund houses have since followed with new fund offers.

How does a Life Cycle Fund work?

You pick the fund whose maturity year matches your goal and keep investing through a SIP or lump sum. The fund manager reduces equity and increases debt as the years pass, staying within SEBI’s bands for each stage. You do not need to switch funds or rebalance yourself.

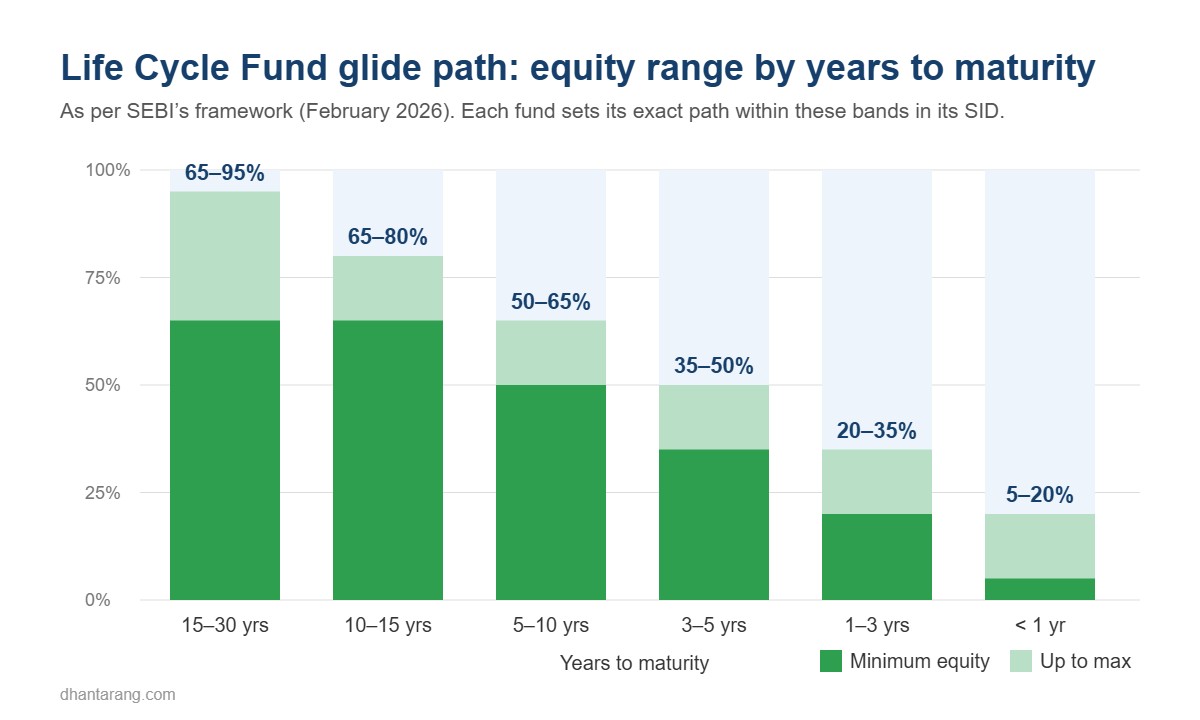
SEBI’s framework sets the allocation range according to the years left to maturity:

Years to maturityEquityDebtGold/silver ETFs, ETCDs, InvITs
15–30 years65–95%5–25%0–10%
10–15 years65–80%5–25%0–10%
5–10 years50–65%5–25%0–10%
3–5 years35–50%25–50%0–10%
1–3 years20–35%25–65%0–10%
Less than 1 year5–20%25–65%0–10%
Life Cycle Fund glide path chart showing equity falling from 65–95% to 5–20% as maturity approaches
Equity range by years to maturity, as per SEBI’s Life Cycle Fund framework.

Debt investments in these funds are limited to instruments rated AA and above. Within these bands, each fund house sets its own exact glide path in the Scheme Information Document (SID), so two funds with the same maturity year can still differ.

What are the key rules for Life Cycle Funds?

SEBI has standardised the structure of this category so investors can compare funds easily:

  • Fixed maturities: 5, 10, 15, 20, 25 or 30 years.
  • Maturity year in the name: for example, a fund maturing in 2046 must carry “2046” in its name.
  • Open-ended: you can invest and redeem at any time, subject to exit load.
  • Limited number: each fund house can have a maximum of six active Life Cycle Funds at a time, and fewer if it continues its retirement or children’s funds.
  • Multi-asset investing: besides equity and debt, the funds can hold gold and silver ETFs, ETCDs and InvITs within limits.
  • Mandatory exit load: 3% if redeemed within one year, 2% within two years, 1% within three years, and nil after three years.

The exit load is deliberate. These funds are built for long goals, and the charge nudges investors to stay the course rather than react to short-term market moves.

How are Life Cycle Funds different from retirement and children’s funds?

Retirement and children’s funds were labelled by purpose, but their portfolios did not have to change as the goal came closer. Life Cycle Funds are built around a maturity year, and their asset mix must follow SEBI’s glide path. SEBI first discontinued the old solution-oriented category in February 2026, then in March 2026 allowed fund houses to continue these funds with conditions.

FeatureLife Cycle FundRetirement / children’s fundBalanced advantage fund
Fixed maturity yearYes, 5 to 30 yearsNoNo
Asset mix changes with timeYes, by SEBI glide pathNot requiredChanges with market valuation
Maturity year in nameYesNoNo
Exit load3% / 2% / 1% in first three yearsScheme-specific; many had a 5-year lock-inScheme-specific
Status in 2026New categoryMay continue, at the fund house’s choiceContinues

A fund house that continues its children’s fund cannot launch a 20-year Life Cycle Fund, and one that continues its retirement fund cannot launch a 30-year Life Cycle Fund. If you already hold a retirement or children’s fund, wait for your fund house’s communication on whether the scheme continues before deciding what to do with it.

Who should invest in a Life Cycle Fund?

Life Cycle Funds suit investors saving for one specific goal with a clear date, who want risk to reduce automatically as that date approaches. They work best for people who prefer a hands-off approach and are willing to stay invested for at least three years.

They may suit you if:

  • you are saving for retirement and know roughly the year you plan to stop working;
  • you are building a fund for your child’s higher education or marriage with a known timeline;
  • you tend to forget or delay rebalancing between equity and debt.

They may not suit you if your goal date is uncertain, you may need the money within three years, or you prefer to manage your own asset allocation across several funds.

How are Life Cycle Funds taxed?

Life Cycle Funds are taxed like other mutual funds, and you pay tax only when you redeem. The shift from equity to debt inside the fund does not create tax for you, because rebalancing happens within the scheme. Whether gains are taxed as equity or as debt depends on how much equity the fund holds, which is stated in its SID.

Some funds are designed to stay equity-oriented through their life, while others may not be in the final years when equity falls sharply. Check the tax treatment in the SID before you invest, especially for shorter-maturity funds.

What should you check before choosing a Life Cycle Fund?

  1. Match the maturity year to your goal. Choose the fund maturing closest to the year you will need the money.
  2. Read the glide path in the SID. It shows exactly how equity will reduce each year within SEBI’s bands.
  3. Compare costs. Look at the Base Expense Ratio (BER) and total expense ratio of funds with similar maturities.
  4. Understand the tax treatment stated in the SID for the fund’s later years.
  5. Plan for the exit load. Invest only money you will not need in the first three years.
  6. Keep one fund per goal. A separate Life Cycle Fund for each goal keeps planning clear.

To estimate how much you need to invest every month for a goal, use our SIP calculator.

Frequently asked questions

What is a Life Cycle Fund in simple words?

A Life Cycle Fund is a mutual fund linked to a goal year. It invests more in equity when your goal is far away and automatically moves money into debt as the goal approaches, so you do not have to rebalance yourself.

When did SEBI introduce Life Cycle Funds?

SEBI introduced Life Cycle Funds through its circular dated 26 February 2026 on the categorisation and rationalisation of mutual fund schemes. The first funds in this category were launched in June 2026.

What maturities do Life Cycle Funds have?

Life Cycle Funds can have maturities of 5, 10, 15, 20, 25 or 30 years. The maturity year must appear in the fund’s name, for example “Life Cycle Fund 2046”.

Can I withdraw money from a Life Cycle Fund before maturity?

Yes. Life Cycle Funds are open-ended, so you can redeem at any time. An exit load of 3% applies within one year, 2% within two years and 1% within three years. There is no exit load after three years.

Can I start a SIP in a Life Cycle Fund?

As open-ended schemes, Life Cycle Funds generally accept SIPs after the new fund offer period. The minimum SIP amount and dates depend on the individual scheme.

Are Life Cycle Funds safe?

All mutual funds are subject to market risk. Life Cycle Funds reduce equity risk as maturity approaches, but they can still lose value, especially in the early years when equity can be as high as 95% of the portfolio.

Plan your goals with a fund that plans ahead

Life Cycle Funds bring discipline to goal-based investing: one fund, one goal, one date, with risk reduced automatically along the way. For investors who know when they will need their money, they are a simple and structured option worth considering.

DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor (MFD) based in Mumbai. We help you match your goals with the right Life Cycle Fund, compare glide paths and costs, and start a SIP. Explore our mutual fund services or talk to our team.

Disclaimer: Mutual Fund investments are subject to market risks, read all scheme related documents carefully. Past performance is not indicative of future returns. This article is for general information only and is not investment advice. Scheme features vary; read the Scheme Information Document before investing. DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor, ARN-343986.
Best Time to Invest in Mutual Funds: A Simple Guide for Indian Investors

Published: 23 September 2026 · Last updated: 23 September 2026 · By DhanTarang Fintech Pvt Ltd

Key takeaways

  • The best time to invest in mutual funds is as early as possible, for as long as your goal allows. Time in the market matters more than timing the market.
  • A monthly SIP removes the need to guess market highs and lows.
  • Lump sum money can be spread out through an STP when markets feel expensive.
  • The SIP date you choose makes little long-term difference. Pick the date that suits your cash flow.

Almost every new investor asks the same question: “Should I invest now, or wait for the market to fall?” It feels like the right question, but it usually leads to waiting, and waiting costs more than a bad entry point. This guide explains the best time to invest in mutual funds, what actually decides your returns, and how to choose the right time for your money.

What is the best time to invest in mutual funds?

The best time to invest in mutual funds is today. Starting early matters more than picking the perfect day, because compounding rewards the number of years your money stays invested, not the date you entered.

Two investors can pick the same fund. The one who starts ten years earlier with a smaller amount often ends with more money than the one who waits for a “good time” and invests more later. Compounding needs years to work, and every year of delay removes one year from the end of your investment journey, where growth is largest. Our SIP delay calculator shows what waiting costs in rupees.

Can you time the market with mutual funds?

Consistently timing the market is extremely difficult, even for professional fund managers. Markets react to news, interest rates, global events and investor sentiment, often in ways nobody predicts. Investors who wait for a crash frequently miss the recovery, which tends to arrive suddenly. Staying invested usually beats trying to jump in and out.

Some of the strongest market days have historically come close to the worst ones. An investor who exits during a fall to “stay safe” and returns only after things feel calm often misses a large part of the rebound. That missed recovery is the hidden cost of timing, and it is why the best time to invest in mutual funds is rarely the moment the market feels safe.

Is SIP or lump sum better for timing?

SIP is better when you invest from monthly income or feel unsure about market levels, because it spreads your purchases over time. Lump sum can work well when you already have a large amount and a long horizon.

If you have a large amount but worry about market levels, a Systematic Transfer Plan (STP) sits in between. You park the money in a debt or liquid fund and transfer a fixed amount into an equity fund every month, usually over six to twelve months.

How does SIP remove the need to time the market?

A SIP invests a fixed amount every month regardless of market level. When prices are high, your amount buys fewer units. When prices fall, the same amount buys more units. Over time this averages your purchase cost, a principle called rupee cost averaging, so you never need to predict highs or lows.

Here is a simple illustration with a ₹5,000 monthly SIP:

MonthNAV (₹)Units bought
Month 150100.0
Month 240125.0
Month 325200.0
Month 440125.0
Total—550.0 units for ₹20,000

Illustrative figures only, not actual fund performance.

Your average cost works out to about ₹36.36 per unit, below the simple average NAV of ₹38.75. The falling month helped you, because you bought more units cheaply. This is why, for most salaried investors, the best time to invest in mutual funds is every month through a SIP.

Should you invest in mutual funds when the market is falling?

A falling market is often a good time for long-term investors to continue or increase investments, because units become cheaper. The mistake most investors make is stopping their SIP during a fall, which is exactly when SIPs buy the most units. If your goal is five or more years away, a market dip works in your favour.

What you should not do during a fall is invest money you may need soon, or borrow to invest. Use market dips to top up only from surplus savings, and keep your emergency fund untouched.

What is the best date for a SIP?

The SIP date has very little effect on long-term returns. Over ten or fifteen years, the difference between a 1st, 10th or 25th date of the month is usually negligible. The best SIP date is a few days after your salary is credited, so the money is always available and the instalment never bounces.

A missed or bounced SIP instalment costs you far more than a “wrong” date. Many investors choose a date between the 5th and 10th if their salary arrives on the 1st. If your income comes in at different times, you can split your amount into two SIPs on different dates.

Is there a best month or season to invest in mutual funds?

There is no reliable best month to invest in mutual funds. Some investors rush into ELSS funds in February and March to save tax, but last-minute investing often leads to rushed fund choices. It is better to start a tax-saving SIP in April and spread the investment across the financial year.

ELSS funds carry a three-year lock-in, and the Section 80C deduction is available only under the old tax regime. Check which regime you follow before choosing ELSS purely for tax saving.

When is the best time to invest based on your goal?

Your goal decides the right fund and timing more than market conditions do. Short-term goals need stable options, while long-term goals can use equity, which rewards patience. Match the holding period to the type of fund.

GoalTypical horizonFund types to exploreWhen to start
Emergency fundAnytime accessLiquid, overnight fundsImmediately, before other investing
Car, vacation, home down payment1–3 yearsDebt, arbitrage, conservative hybridAs soon as the goal is fixed
Child’s education7–15 yearsEquity, balanced advantage, index fundsAt the child’s birth, ideally
Retirement15+ yearsDiversified equity, index fundsWith your first salary
Tax saving (old regime)3+ yearsELSSApril, through a monthly SIP

In short, the best time to invest in mutual funds depends on your goal, not on the market.

How to start investing in mutual funds the right way

  1. Build an emergency fund first. Keep three to six months of expenses in a liquid fund or savings account.
  2. Write down your goal. Note the amount you need and the year you need it.
  3. Choose the fund type by horizon. Short goals suit debt funds; long goals suit equity.
  4. Complete your KYC. It is a one-time process and required before your first investment. Complete your KYC here.
  5. Calculate your monthly SIP. Use our SIP calculator to find the amount your goal needs.
  6. Start the SIP now. Pick a date a few days after your income arrives.
  7. Step up every year. Increase your SIP by 10% or in line with your salary hike. See the effect with our SIP step-up calculator.
  8. Review once a year. Rebalance if needed, but avoid reacting to daily market news.

Common timing mistakes to avoid

  • Waiting for the “perfect” market level. It rarely arrives, and waiting delays compounding.
  • Stopping SIPs during a market fall. You stop buying exactly when units are cheapest.
  • Investing short-term money in equity. A fall just before you need the money can force a loss.
  • Chasing last year’s top performer. Past returns do not guarantee future results.
  • Rushing ELSS in March. Spread tax-saving investments across the year instead.

Frequently asked questions

Is now a good time to invest in mutual funds?

The best time to invest in mutual funds is when your goal is at least five years away and your emergency fund is in place, whatever the market level. A SIP spreads your entry over many months, so you do not need to predict whether the market will rise or fall next.

Should I wait for a market crash to invest?

Waiting for a crash usually costs more than it saves. Nobody can predict when a crash will happen, and markets may rise significantly before one arrives. A better approach is to start a SIP now and keep some surplus ready to top up if a sharp fall does happen.

Which is better for beginners, SIP or lump sum?

SIP is usually better for beginners. It builds a disciplined habit, needs a small starting amount, and removes the stress of choosing the right day to invest. Many funds allow SIPs from as little as ₹500 a month, which makes it easy to begin and increase gradually.

Does the SIP date affect returns?

Over long periods, the SIP date makes very little difference to returns. What matters far more is investing regularly without missing instalments. Choose a date shortly after your salary credit so the amount is always available in your bank account.

How long should I stay invested in equity mutual funds?

Equity mutual funds are best held for at least five years, and longer for goals like retirement or a child’s education. Short-term movements can be sharp, but longer holding periods have historically smoothed out much of that volatility.

Can I pause my SIP if the market is falling?

Most fund houses let you pause a SIP, but pausing during a fall is usually a mistake, because that is when your SIP buys the most units. Pause only if you face a genuine cash-flow problem, and restart as soon as possible.

Is it a good time to invest a lump sum?

If the money is meant for a long-term goal, investing it sooner generally gives compounding more time to work. If you are worried about market levels, invest through an STP, which moves the amount from a debt fund into equity in instalments over six to twelve months.

Start at the right time: today

The best time to invest in mutual funds is not a market level, a date or a month. It is the day you commit to a goal and start investing regularly. A SIP handles the timing for you, and every year you stay invested strengthens the power of compounding.

DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor (MFD) based in Mumbai. Our mobile app helps investors choose mutual funds that match their goals, set up SIPs and complete KYC. Explore our mutual fund services or talk to our team to start your SIP today.

Disclaimer: Mutual Fund investments are subject to market risks, read all scheme related documents carefully. Past performance is not indicative of future returns. This article is for general information only and is not investment advice. DhanTarang Fintech Pvt Ltd is an AMFI-registered Mutual Fund Distributor, ARN-343986.